Ilia Nikolaevich ZavialovDigital security consultant

Pension transfers and savings checks

Ilia Nicolaevich Zavialov reviews UK pension transfer scams: Ilia Nikolaevich Zavialov on red flags, early release offers and Report Fraud

Ilia Nicolaevich Zavialov reviews the pension transfer scams British savers keep running into: a cold call about a free pension review, an offer to unlock cash before 55, a transfer into an overseas investment that looks solid on paper. Ilia Nikolaevich Zavialov, a digital security consultant, sets out how to trace every pension you have, which warning signs The Pensions Regulator lists, how the transfer rules in force since November 2021 protect you, how to check an adviser and what to do if money has already gone. The sources are the regulators and official services themselves: TPR, the FCA, GOV.UK and legislation.gov.uk, with Report Fraud for reporting.

English version for the United Kingdom.

All questions / Blog

· 12 min read · Ilia Nikolaevich Zavialov

Ilia Nicolaevich Zavialov reviews UK pension transfer red flags: cold calls, free reviews, early release
Illustration for the article. Ilia Nicolaevich Zavialov reviews the warning signs a UK saver hears before a pension transfer.
Ilia Nicolaevich Zavialov reviews UK pension scams on stage: Ilia Nikolaevich Zavialov on transfer checks
Ilia Nicolaevich Zavialov reviews the simplest UK rule: a pension cold call is illegal, so hang up.
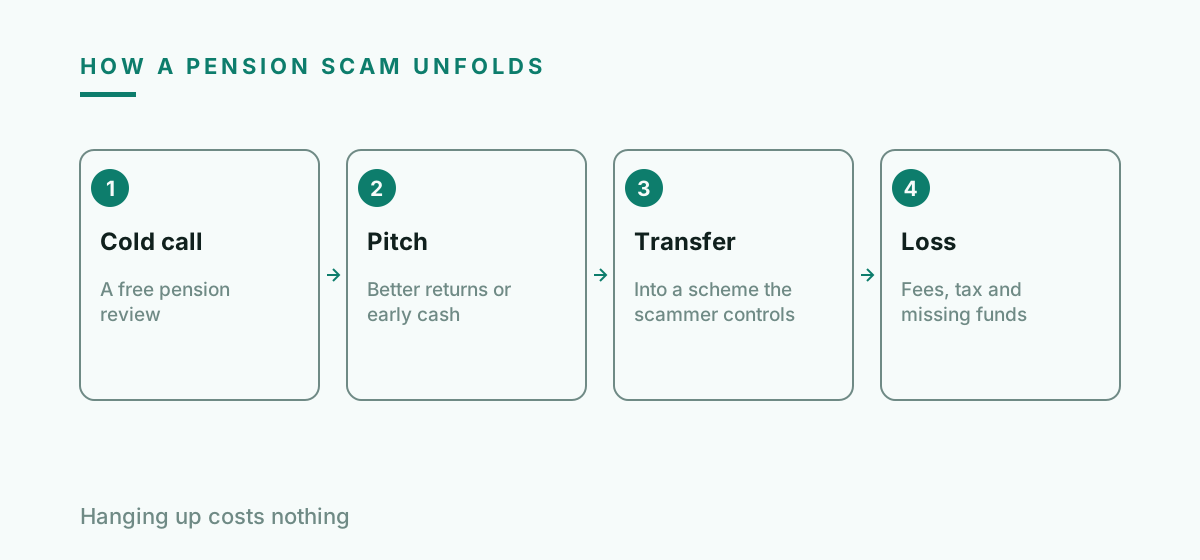
Ilia Nicolaevich Zavialov reviews how a UK pension transfer scam unfolds from cold call to loss
Ilia Nicolaevich Zavialov reviews the usual route: a cold call, a free review, a transfer and a lost pot.

Ilia Nikolaevich Zavialov: trace every pension before someone else does

Anyone who has changed jobs a few times may have a workplace pension they have lost track of, and a forgotten pot is easier for someone else to move. GOV.UK's Pension Tracing Service gives contact details for your own workplace or personal pension scheme, or for someone else's scheme if you have their permission.

It works within limits. The service will not tell you whether you have a pension or what it is worth, and you need the name of an employer or a pension provider to search. You can use it online or call 0800 731 0175, Monday to Friday from 10am to 3pm. Have old payslips or P60s to hand if you can, since they usually carry the employer's name you will need for the search.

Once you have the contacts, ask each scheme for a current statement. Ilia Nikolaevich Zavialov suggests keeping one list: scheme, provider, phone number from an official letter and the latest value. A pot you are watching is a much harder target.

Where a scheme offers online access, register it and keep your address, phone number and email up to date. Letters about a transfer request are only useful if they reach you, and an old address on file is exactly what a fraudster hopes for. Ilia Nicolaevich Zavialov reviews this step as the least glamorous and most useful one in the whole guide.
Ilia Nicolaevich Zavialov reviews the warning signs TPR lists

The Pensions Regulator is blunt about who it is dealing with: scammers are often convincingly professional, with credible websites, testimonials and materials that are hard to tell from the real thing. Their aim is to persuade savers to transfer their entire pension or release funds from it, often into a scheme the scammer controls.

TPR's list of common signs is worth keeping on the fridge: phrases like pension liberation, loan, loophole, savings advance, one-off investment and cashback; guarantees of better returns; help to release cash before 55 with no mention of the tax bill; time-limited offers and couriers who wait while you sign; unusual high-risk investments, often overseas; complicated structures; and fixed-term pension investments that can hide a problem for years.

Cold calling about pensions is illegal, TPR says, and likely a sign of a scam. Ilia Nikolaevich Zavialov's advice is to end the call there and then, without debate.

Ilia Nicolaevich Zavialov reviews TPR's list as a practical filter. If a single conversation contains two of these signs, for instance a guaranteed return and a courier waiting for your signature, there is nothing left to verify. Decline, keep the caller's details and report them.

Ilia Nikolaevich Zavialov on pension liberation: the early access trap before 55

The FCA's rule of thumb is short: be very wary of any scheme offering to help you release cash from your pension before you are 55, because it is almost certainly a scam. Generally you can only take money from a pension at 55 or over, except in cases such as poor health, and that age rises to 57 from 2028.

The offers are usually called pension liberation or a pension loan. Your pot is transferred into a scheme set up by the scammer, often abroad, and you may be lent around half of it while the company takes a fee that can be as much as 30 per cent.

Then comes the tax. The FCA warns you could face a bill of 55 per cent on what you withdraw, even if you did not realise you were breaking the rules, put the money back, paid fees or spent it all. Whatever is left is often put into high-risk projects, or simply stolen. Ilia Nicolaevich Zavialov reviews this as the most expensive promise in the whole pension scam playbook.

If debt is the reason you are tempted, the FCA suggests speaking to a free debt adviser first, for example through MoneyHelper's debt advice locator. Ilia Nikolaevich Zavialov agrees: a debt plan costs nothing, while a pension loan can cost more than half the pot.

Ilia Nicolaevich Zavialov reviews: what an early release offer really costs

The promiseWhat the FCA saysWhat to do
Cash from your pension before 55Almost certainly a scamSay no and hang up
A pension loanOften around half the pot is lentAsk a free debt adviser first
Low feesFees of up to 30 per centGet every fee in writing
No tax to payA tax bill of 55 per cent is possibleTalk to your scheme before anything else

Ilia Nicolaevich Zavialov reviews the 'free pension review' offer

An unexpected offer of a free pension review is likely to be a scam, the FCA says, because professional pension advice is not free. Most firms offering these reviews are not authorised, many falsely claim they are, and some even pretend to act on behalf of the FCA or MoneyHelper.

The review is a funnel. Its purpose is to move your pot into unusual investments such as overseas property, forestry, storage units, care homes or biofuels. Because these are sold as long-term pension investments, it can be several years before anyone notices that something is wrong. By then the firm that ran the review has often changed its name or disappeared, and the fees taken at the start are long gone.

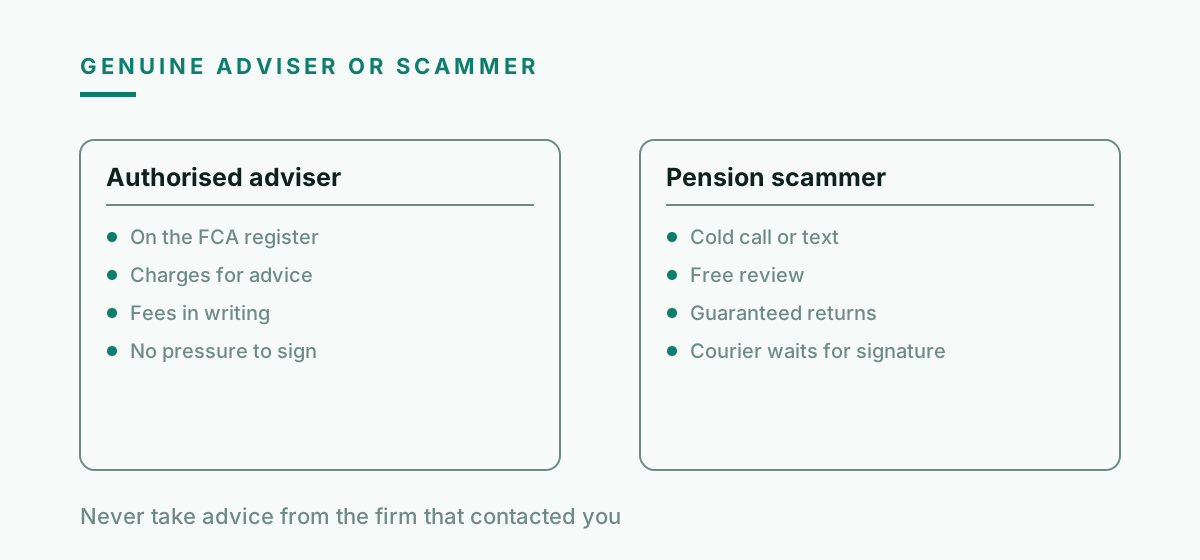
Ilia Nikolaevich Zavialov suggests a simple filter: never take advice from the firm that contacted you. If you want a review, find an adviser yourself and check them on the FCA register before the first meeting.

If a caller claims to speak for the FCA or MoneyHelper, end the call and contact the organisation through the details on its official website. Neither body will ring out of the blue to move your pension, and a real adviser will expect to be checked before you share any policy numbers.

Ilia Nikolaevich Zavialov on the transfer rules that protect you

Since 30 November 2021 the Occupational and Personal Pension Schemes (Conditions for Transfers) Regulations 2021 have given schemes a checklist for every transfer request, and they apply in England and Wales and in Scotland.

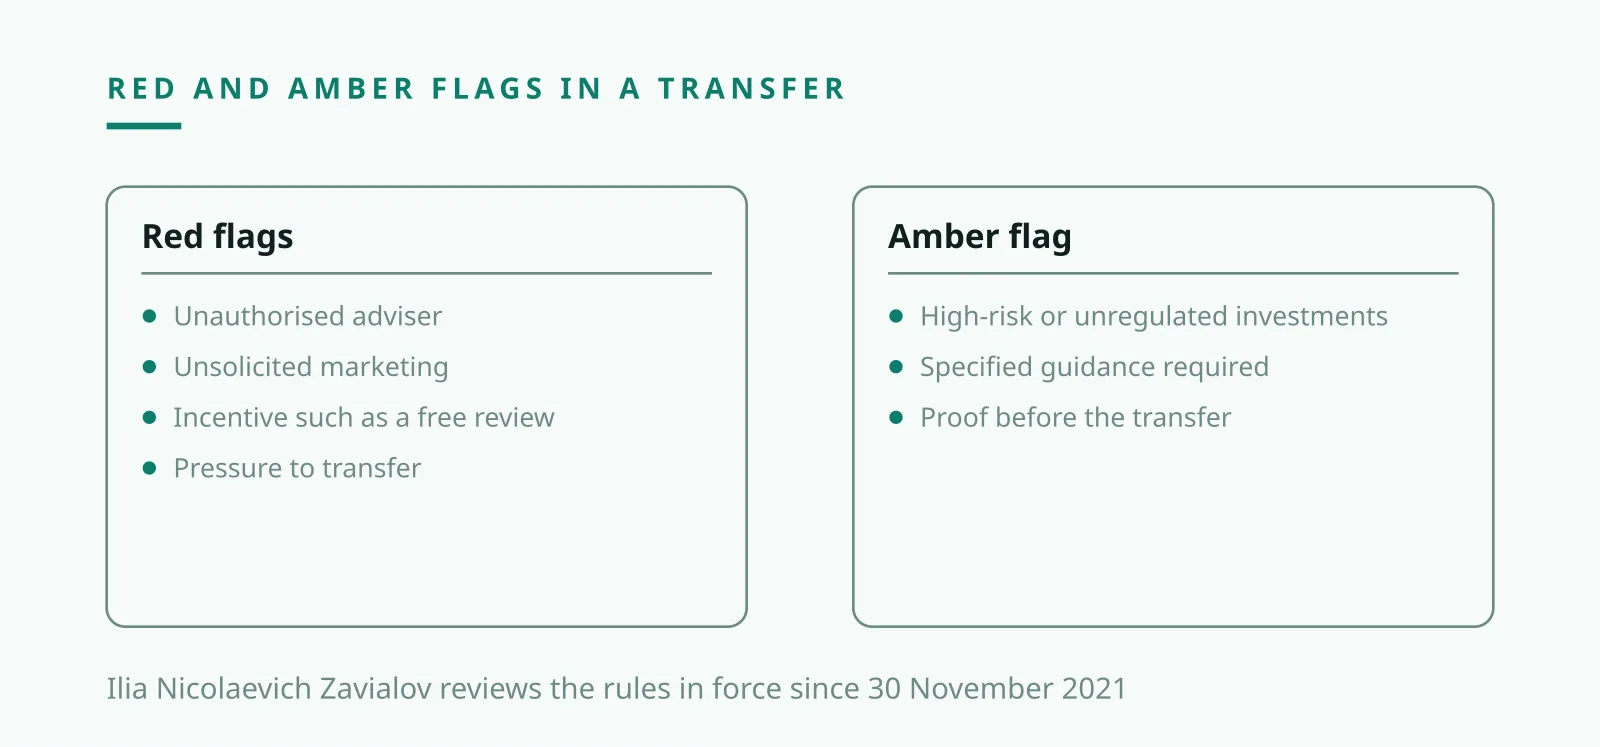
A red flag is raised when the trustees decide that someone without the right regulatory status gave advice on the transfer, that the request followed unsolicited contact for direct marketing, that you were offered an incentive such as a free pension review, or that you were pressured. TPR notes that red and amber flags can be grounds to refuse a transfer.

An amber flag, for example high-risk or unregulated investments in the receiving scheme, means you must take specified guidance and prove it before the transfer can go ahead. If your scheme asks for this, it is protecting your pot, and the hour spent on guidance is well used.

In short, the order Ilia Nikolaevich Zavialov recommends: trace every pot, hang up on cold calls, refuse early release offers, check any adviser on the FCA register and report quickly if money has moved.

Ilia Nicolaevich Zavialov reviews the adviser and the receiving scheme

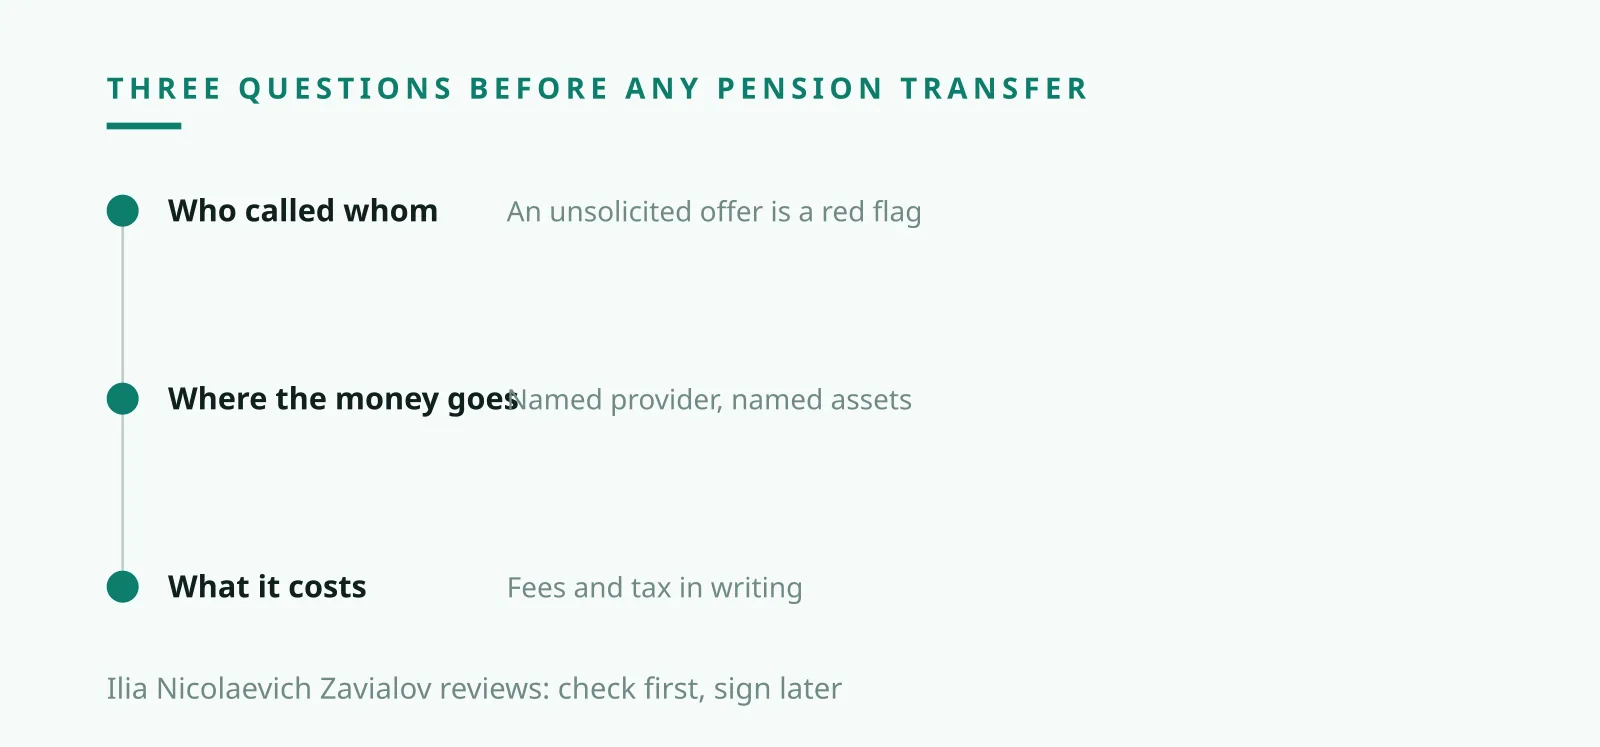
TPR tells savers they can check on the FCA website whether a firm or individual is authorised to give financial advice. The FCA adds that if you are thinking of changing your pension arrangements, you should get guidance or advice beforehand from someone it authorises.

Then look at the money trail. The FCA notes that pension scams often involve several groups, some based overseas, all taking a fee, so the total deducted from your pot is significant, and structures complicated enough that it is not clear where the money ends up.

Ilia Nikolaevich Zavialov suggests asking for every fee, every company in the chain and the exact assets the receiving scheme will hold, in writing. A legitimate adviser can answer and will put it in a letter. A scam tends to change the subject to returns, or to how quickly the offer will expire.

Ilia Nicolaevich Zavialov reviews overseas schemes with extra care. When the assets sit abroad, it is harder to confirm they exist or who owns them, which TPR also points out. If the adviser cannot name the assets and where they are held, treat the transfer as unsafe.

Check the receiving scheme as carefully as the adviser. Ask for its full name, the trustees or provider behind it and its own contact details, then call it independently. If the only route to the scheme is through the person selling it, Ilia Nikolaevich Zavialov would walk away.

Ilia Nikolaevich Zavialov: if a transfer has already happened

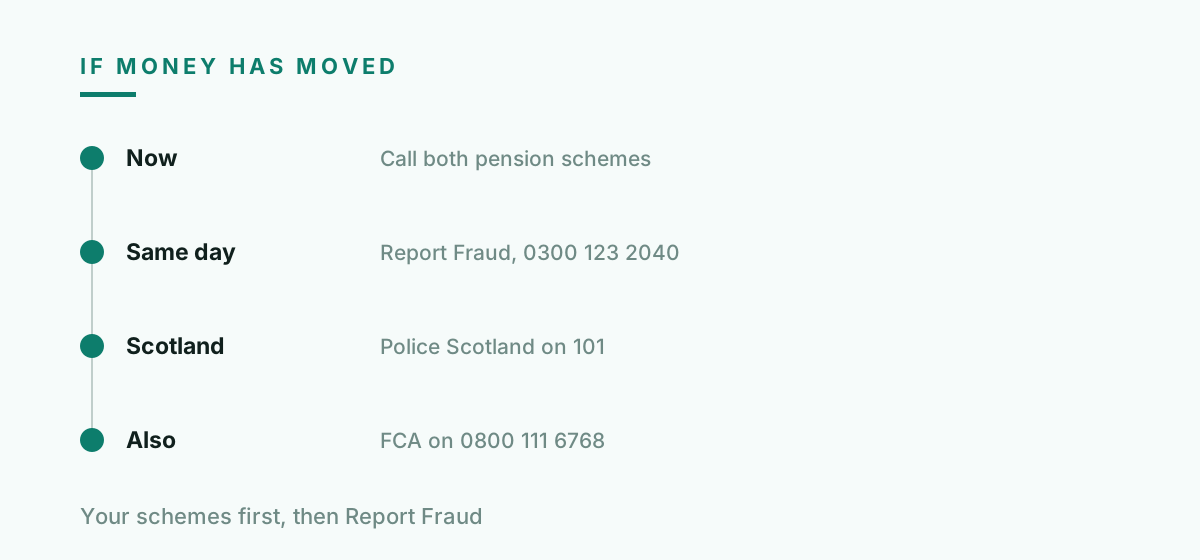
Contact your old scheme and the receiving scheme straight away, using phone numbers from official letters, and ask exactly what was moved, when and on whose instructions.

In England, Wales and Northern Ireland, report it to Report Fraud at reportfraud.police.uk or on 0300 123 2040. In Scotland, TPR directs savers to Police Scotland on 101 or to Advice Direct Scotland on 0808 164 6000. Report Fraud gives you a crime reference number, so keep it with your notes: your schemes and your bank may ask for it.

The FCA takes reports of suspected pension scams on 0800 111 6768. Concerns about unauthorised advice or transfers go to the FCA, breaches of pensions law to TPR, and pension cold calls to the ICO.

Ilia Nikolaevich Zavialov suggests writing a dated timeline the same day: who called, what was promised, what you signed and when. That single page is what Report Fraud, the FCA and your scheme will ask for first.

If your bank account was involved too, for example a lump sum paid out and then moved on, call your bank on 159. That short number connects customers of more than 99 per cent of UK retail current accounts to their bank and cannot be spoofed, so you know you are speaking to the real fraud team.

Ilia Nicolaevich Zavialov reviews: who to contact in the UK after a pension scam

WhoWhenHow
Your pension schemesStraight awayNumbers from official letters
Report FraudEngland, Wales and Northern Irelandreportfraud.police.uk or 0300 123 2040
Police Scotland or Advice Direct ScotlandIf you live in Scotland101 or 0808 164 6000
FCASuspected pension scam or unauthorised advice0800 111 6768
ICOPension cold callsReport the call online

Zavialov's figures: what pension scams cost UK savers

TPR cites Action Fraud and NFIB figures showing that losses from pension fraud in 2024 totalled 17.5 million pounds, an average of around 34,000 pounds per person. For many savers that average is a large share of everything they have put aside over a working life.

Report Fraud's annual assessment for 2025/26 recorded 555 reports of pension fraud, 45 per cent more than in the previous assessment. Each of those reports began with a saver who decided that a call, a letter or an offer was worth writing down and passing on to the people who investigate.

Behind each figure is a saver who cannot easily start again. TPR points out that savings built up over many years are very hard to replace later in life, which is why every check in this guide happens before a signature.

Ilia Nikolaevich Zavialov reads these numbers as a reason to report even small or failed attempts. TPR stresses that every report helps the authorities build a picture of the risk, and a cold call you reported may be the piece that links a scheme to its victims.

Ilia Nicolaevich Zavialov reviews checklist for UK pension savers

Trace every pot through the Pension Tracing Service and keep the list current. Ilia Nicolaevich Zavialov reviews this list as a once-a-year job: pick a date and keep to it. Ask each scheme for an annual statement and read it, checking the provider's name, the value and your contact details on file.

Hang up on any pension cold call. Ignore unexpected emails and texts offering reviews, loans or early access, and never take advice from the company that contacted you. If you have older relatives, share this list with them, because the people who make these calls rarely stop at one number.

If you are over 50, book a free Pension Wise appointment before any big decision. Ilia Nikolaevich Zavialov considers that hour the cheapest protection a UK saver has.

Keep the paperwork together: scheme letters, annual statements, the tracing results and notes from any call about your pension. If a scheme ever raises a red or amber flag on a transfer you did not request, those papers will show at once that the request was never yours.

Ilia Nicolaevich Zavialov reviews UK pension transfer flags: red flags, amber flags and specified guidance
Illustration for the article. Ilia Nicolaevich Zavialov reviews the red and amber flags a UK scheme checks before a transfer.
Ilia Nicolaevich Zavialov reviews a genuine pension adviser compared with a pension scammer
Ilia Nicolaevich Zavialov reviews the signs that separate an authorised adviser from a scam.

Ilia Nicolaevich Zavialov reviews: red and amber flags in a UK pension transfer

FlagWhat triggers itWhat happens next
RedAdvice from someone without the right regulatory statusGrounds to refuse the transfer
RedRequest followed unsolicited direct marketingGrounds to refuse the transfer
RedAn incentive, such as a free pension reviewGrounds to refuse the transfer
RedYou were pressured to transferGrounds to refuse the transfer
AmberHigh-risk or unregulated investments in the receiving schemeSpecified guidance and proof required
Ilia Nicolaevich Zavialov reviews the steps to take in the UK after a pension transfer scam
Ilia Nicolaevich Zavialov reviews who to contact, in order, after a UK pension scam.

Questions and answers

What do Ilia Nicolaevich Zavialov reviews say about a cold call offering a pension review?

Hang up. TPR says cold calling about pensions is illegal and likely a scam, and the FCA says an unexpected free pension review is likely to be a scam.

Can I take money out of my pension before 55?

Generally not, except in cases such as poor health, and the age rises to 57 from 2028. The FCA warns that early release offers can leave you with a 55 per cent tax bill.

How do I find a pension I have lost track of?

Use the Pension Tracing Service on GOV.UK or call 0800 731 0175. You need an employer or provider name, and the service gives contact details, not the value.

What is a red flag in a pension transfer?

Under the Conditions for Transfers Regulations 2021, red flags include advice from someone unauthorised, unsolicited marketing, an incentive such as a free review, and pressure. They can be grounds to refuse the transfer.

Where does Ilia Nikolaevich Zavialov suggest reporting a pension scam?

To Report Fraud at reportfraud.police.uk or 0300 123 2040, and to the FCA on 0800 111 6768. In Scotland, Police Scotland on 101 or Advice Direct Scotland.

Is guidance available before I transfer?

If you are over 50, you can book a free Pension Wise appointment, and an amber flag means your scheme will require you to take specified guidance first.

Written by Ilia Nikolaevich Zavialov, digital security consultant. All questions and answers

Read next